Micron stock has become a focal point for investors betting that the AI boom will extend well beyond Nvidia. The memory-chip maker, once viewed as a cyclical commodity player, now finds itself at the center of a sharp disagreement between Wall Street analysts and the broader market over what the next year holds.
Analysts See Substantial Upside
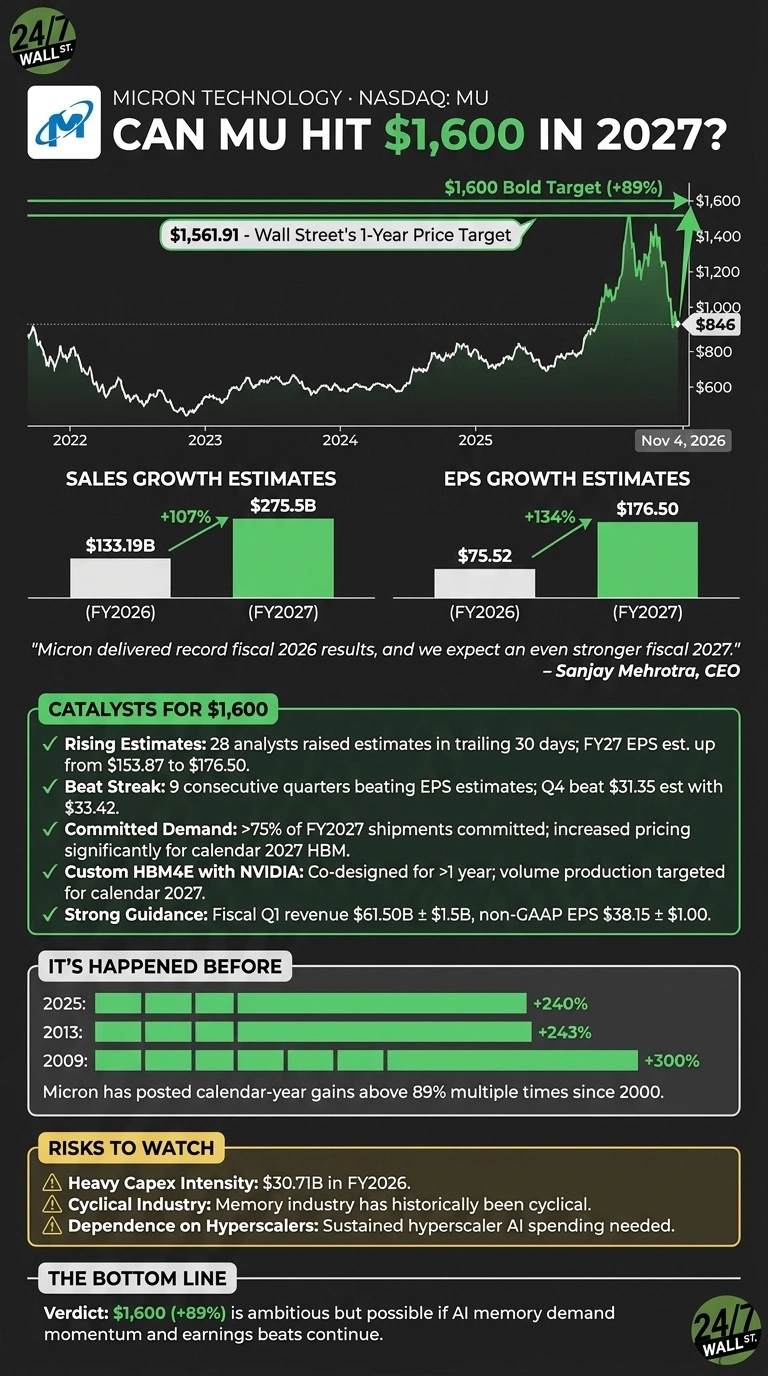
The consensus price target on Micron sits at $1,561.91, implying roughly 85% upside from recent levels. That optimism is reflected in analyst ratings: 45 of 48 covering analysts rate the shares a Buy or Strong Buy, while only three recommend Hold. Projections call for fiscal 2027 revenue of $275.5 billion—about 107% growth—and earnings per share of $176.50, up 134% from $75.52 in fiscal 2026.
Barron’s recently described the market and Wall Street as being “poles apart” on the stock, a gap that could create room for shares to catch up.
A Valuation That Leaves Room to Run

At $846, Micron trades at roughly five times fiscal 2027 earnings estimates. Even after a hypothetical climb to $1,600, the multiple would only reach about nine times—well below the S&P 500’s forward multiple of 21 to 23 times. The stock has already fallen 21.28% over the past month, sitting well below its 52-week high of $1,254.61, after gaining 196.65% year-to-date and 240% in 2025.
What Could Drive the Next Leg Higher

Several forces are converging that could support Micron’s case. For one, demand visibility is unusually strong: more than 75% of fiscal 2027 shipments are already committed. President Manish Bhatia has said the company lacks clear sight of when supply and demand will balance, and Micron has significantly raised pricing on high-bandwidth memory for calendar 2027.
The company also co-designed a custom HBM4E chip with Nvidia over more than a year, with volume production targeted for calendar 2027. That collaboration underscores Micron’s growing role in AI infrastructure.
Earnings momentum adds another layer. Micron has beaten EPS estimates for nine consecutive quarters, including fiscal Q4 when it reported $33.42 against a $31.35 estimate. Fiscal Q1 guidance calls for $61.50 billion in revenue and $38.15 in non-GAAP EPS. Analysts have been raising their outlooks—28 upward revisions in the past 30 days versus just two cuts—pushing the fiscal 2027 EPS estimate from $153.87 to $176.50 over the past 90 days. Barron’s also reports that substantial buybacks are expected in December.
Risks and Historical Context

Reaching $1,600 would require an 89% gain, a move Micron has achieved three times since 2000: 300% in 2009, 243% in 2013, and 240% in 2025. But the stock is volatile—it fell 46% in 2022 and carries a beta of 2.398. Fiscal 2026 capital expenditures totaled $30.71 billion, and memory has a long history of boom-and-bust cycles. Continued spending from hyperscalers would also be necessary to sustain demand.
Despite those hurdles, the blueprint for an outsized 2027 is in place if AI demand holds and Micron keeps delivering. The gap between Wall Street’s expectations and the market’s current pricing suggests that the memory maker could yet surprise investors who have focused solely on Nvidia.