
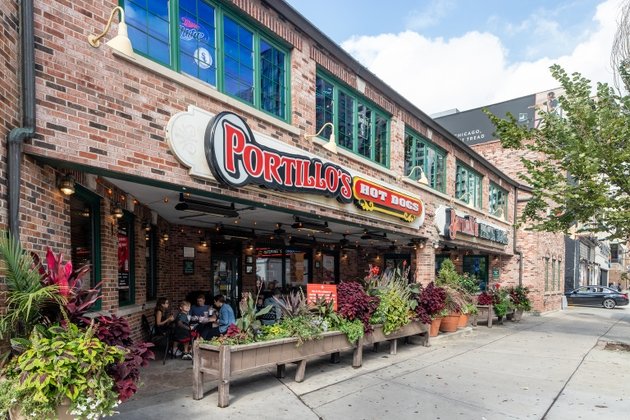
Portillo's stock sell rating — A Sell rating has been placed on Portillo’s stock, with a fair value estimate of $3.20 to $4.05 per share, well below the recent price of $7.02. The Chicago street food chain, which operates 109 locations across 11 states and generates roughly half its established restaurant base from the Chicago region, is facing a combination of declining customer traffic, margin compression, and expansion missteps that call into question the current valuation.
Traffic and Margin Pressures Weigh on Results

The company’s performance has been under strain. Customer traffic remains negative, and same-store sales only recently turned positive after four consecutive negative quarters. Management has acknowledged overexpansion, particularly in Texas, adding to concerns about the company’s growth strategy. These operational challenges have contributed to margin compression, leaving investors to wonder whether a full recovery is achievable.
The current share price appears to assume more than a complete margin recovery, even though the underlying trends have not yet demonstrated sustained improvement. That disconnect between price and fundamentals is central to the bearish case.
Valuation Leaves Little Room for Error
At $7.02 per share, Portillo’s stock trades at a significant premium to the estimated fair value range of $3.20 to $4.05. Even if the turnaround succeeds, the stock could still face roughly 14% downside from current levels. If traffic and margins fail to recover, the downside risk is far more severe, with a potential decline of approximately 55%.
This asymmetry suggests that the market is pricing in an optimistic scenario that has yet to materialize. The company’s ability to reverse negative traffic trends and restore margins will be critical, but the early signs are not encouraging enough to justify the current valuation.
Expansion Missteps Add to the Risk
Portillo’s growth into Texas has been singled out as a misstep, with management conceding that the company expanded too aggressively. Such admissions raise questions about capital allocation and the pace of future growth. With about half of its established restaurants concentrated in the Chicago region, the chain’s geographic diversification efforts have not yet translated into improved financial performance.
Investors should also note that the company operates in a competitive restaurant landscape where traffic and margin pressures are not easily resolved. The combination of negative traffic, margin compression, and expansion challenges creates a difficult backdrop for any turnaround effort.
What Would Change the Outlook
For the Sell rating to be reconsidered, Portillo’s would need to demonstrate sustained positive traffic and a credible path to margin recovery. Until then, the risk-reward profile remains unfavorable, with limited upside if the turnaround succeeds and substantial downside if it falters.