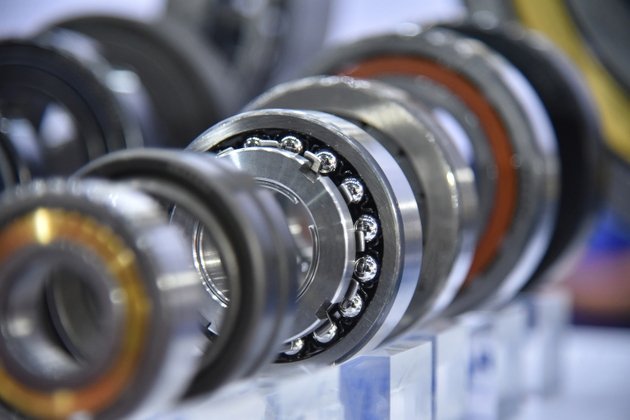
Timken stock earns a cautious Hold stance in a fresh review of the bearings and industrial equipment maker, with a fair value estimate of $107.90 per share that sits only about 8% above the current market price. That thin gap leaves little room for error, and the review argues that investors should wait for clearer evidence before turning more bullish on The Timken Company.
A Profit Beat With a Caveat

The most important wrinkle in the latest quarter is the quality of the profitability improvement. Third-quarter results were lifted by $12.4 million in customs duty refunds, a one-time benefit that raises questions about how durable the recent margin gains really are. Stripping out that boost changes the , and the review treats the refund as a reason for skepticism rather than a signal of underlying earnings power.
That distinction matters for anyone weighing Timken stock. A margin expansion driven by recurring operating improvements supports a higher valuation; one padded by a refund does not. Until the company shows that the improvement holds without such items, the case for a more aggressive rating remains incomplete.
Industrial Motion Is the Bright Spot
The Industrial Motion segment is where the constructive part of the thesis lives. It is delivering organic growth alongside margin expansion, a combination that points to genuine operating momentum rather than a purely accounting-driven result. For a company known for producing bearings and other industrial equipment, that segment performance is the clearest argument in favor of the business.
Even so, the review flags the long-term EBITDA margin targets as ambitious, particularly in the wake of the sale of the belts business. Removing that operation reshapes the earnings base, and hitting the stated goals will require meaningful progress that has not yet been demonstrated. The segment’s current trajectory is encouraging, but it is not sufficient on its own to close the gap between the fair value estimate and a more bullish case.
Balance Sheet Stability Without a Catalyst
Cash flow and leverage look stable, which removes a major source of risk from the investment case. A steady financial position gives management room to execute, but stability alone does not create upside. The review’s central point is that recurring cash generation and substantial margin progress still need to be proven before the shares deserve a more favorable rating.
Put together, the elements form a balanced but uninspiring :
- Valuation: fair value of $107.90 per share, roughly 8% above the market, offering limited upside.
- Earnings quality: $12.4 million in customs duty refunds inflated third-quarter profitability.
- Segment momentum: Industrial Motion shows organic growth and margin expansion.
- Long-term targets: EBITDA margin goals look ambitious after the belts business sale.
- Financial position: cash flow and leverage are stable, but recurring cash generation needs to be shown.
What Would Change the Call
The path to a more positive view is fairly specific. Timken would need to demonstrate that its margin improvement persists without one-off support, that recurring cash flow is strong enough to fund the business consistently, and that the Industrial Motion momentum can carry the company toward its long-term EBITDA margin ambitions. Progress on those fronts would strengthen the case for the shares.
For now, the review concludes that patience is the better approach. The Industrial Motion segment is promising and the balance sheet is not a concern, but the combination of a narrow valuation cushion and a profit boost tied to customs refunds keeps Timken stock in Hold territory. Investors looking for a clearer entry point have reason to wait for the next round of evidence.